

Plynk: Grow as an Investor
Digital Brokerage Services LLC
- 4.1
- 590.00 Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
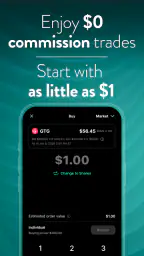
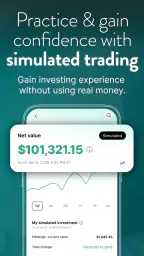
Plynk: Grow as an Investor Pros and Cons
Pros
- Simple interface makes investing approachable for beginners.
- Fractional shares let users invest with smaller amounts.
- Recurring investments can help build consistent saving habits.
- Portfolio insights make it easier to track performance.
- Educational content supports users learning investment basics.
Cons
- Investment values can fall, so returns are never guaranteed.
- Limited investment choices may not suit advanced investors.
- Fees and spreads can reduce returns on smaller investments.
- Some features may vary depending on your country or eligibility.
- Identity checks and account setup may take time to complete.
 Analysis by All-app
I found Plynk: Grow as an Investor most useful as a gentle entry point into investing rather than as a command center for experienced traders. The Finance app from Digital Brokerage Services LLC is built around making investing feel less intimidating, with tools and learning material placed close to the decisions a new investor is likely to face. I used it with that expectation, and it generally delivered a calmer experience than many investing apps that lead with charts, alerts, and dense market language.
That simplicity is the main reason I would recommend it to a friend who wants to start building an investing habit but does not yet know which questions to ask. It is free, rated for Everyone, and available for devices running iOS 12 or later. The app has reached over half a million installs and holds a 4.1 average from around four thousand ratings, which gives a useful sense of its position: established enough to attract a broad audience, but still designed around approachability rather than professional trading.
How I would use Plynk in a normal week
My preferred workflow begins with a short visit rather than constant checking. I open the app, look at the account overview, review what I already own, and then spend a few minutes reading or exploring before making any decision. That order matters. It keeps the app from becoming a place where I react to every market movement, and it makes the educational side part of the routine instead of something I promise to study later.
For someone starting out, the first useful habit is to separate learning from buying. I would use the educational explanations to understand terms, compare an idea with my own goals, and only then decide whether an investment deserves further attention. Plynk’s approachable presentation helps here because it does not make every screen feel like a test of financial knowledge. I still need to do my own research, but I am less likely to abandon the process because of unfamiliar wording.
A realistic everyday example would be a person who receives income, checks regular expenses, and wants to put a small amount toward long-term investing. Instead of opening the app several times a day, that person could choose one weekly review: confirm the available balance, revisit the reason for investing, read one relevant explanation, and record why a purchase is being considered. This turns Plynk into a repeatable planning tool rather than an entertainment feed driven by price changes.
I also like the idea of using the app to build vocabulary before building a portfolio. A beginner who cannot explain the difference between a company share and a broader investment product should not feel pressured to act immediately. The educational material is more valuable when it answers a question that has already come up in the user’s mind. I would keep a short note of unfamiliar terms, look at them when I am not rushed, and return to the investment screen only after the explanation makes sense.
The right starting point for beginners
The app is especially suitable for someone who wants a guided introduction without opening a separate learning platform every time a term appears. Its central appeal is clarity: the experience tries to bring explanations and investing actions into the same general environment. That reduces the friction between “I want to understand this” and “I want to decide what to do next.”
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
However, clarity should not be confused with certainty. A clean interface cannot remove investment risk, and an educational explanation cannot tell me whether an asset fits my finances. I would still decide how much money I can afford to invest, how long I expect to leave it invested, and how comfortable I am with losses before using any investing feature. Plynk makes those conversations easier; it does not replace them.
For a first-time user, I would recommend beginning with observation. Explore the main areas, read the explanations attached to unfamiliar concepts, and notice how much information is available before committing money. This is a better test of whether the app suits you than making a quick purchase simply because the process feels easy.
Settings and habits worth checking
One of the most practical improvements is to decide how often you want to engage with the app before you start. If notifications or market updates encourage you to check constantly, reduce that distraction when the available controls allow it. I would rather open Plynk at a planned time with a clear question than respond to every movement in an account. The best setting is the one that supports your investing plan instead of changing it.
I would also review the account and profile details carefully during setup. Small mistakes in personal information, funding choices, or preferences can create avoidable friction later. Even when an app feels simple, financial applications deserve a slower setup than a casual social app. Read each confirmation, make sure the selected option matches your intention, and avoid rushing through screens just to reach the main dashboard.
Another useful habit is to define a personal review checklist outside the app. Mine would include the purpose of the investment, the intended time horizon, the amount involved, and the reason I am considering it. Plynk can help me explore an idea, but a checklist prevents the interface from becoming the decision-maker. This is particularly important when an investment looks attractive simply because it is easy to find or understand.
I would keep educational exploration and portfolio maintenance as two separate activities. During one session, I might learn about a concept; during another, I might review what I already own. Combining both can make a short visit feel productive, but it can also encourage impulsive action immediately after reading something persuasive. A pause between learning and buying is a simple safeguard that experienced users often value.
Faster patterns that do not encourage impulsive decisions
Once the basic workflow feels familiar, the fastest approach is not constant speed. It is reducing repeated uncertainty. I would write down the questions I ask before every investment and reuse that same sequence. Does this fit my goal? Do I understand what I am buying? Can I tolerate a decline? Am I acting because of a plan or because of a recent headline? A repeatable sequence makes the app easier to use while keeping judgment in my hands.
I would also make use of short, focused sessions. One visit can be for learning, another for reviewing holdings, and another for checking whether a planned contribution still fits the budget. This separation makes it easier to notice when I am drifting from long-term investing into frequent speculation. Plynk’s accessible design supports this kind of routine because I do not need to treat every opening as a full research project.
For a new investor, a useful shortcut is to begin with a familiar financial objective rather than a search for the “best” investment. Saving for a long-term goal creates a filter for the information on screen. Without that filter, even a clear app can present too many interesting possibilities. With it, I can reject ideas that do not match my time frame or risk tolerance before spending energy on them.
Another efficient pattern is to review decisions after making them. I would note what I expected, what could go wrong, and what would cause me to reconsider. The purpose is not to predict the market perfectly. It is to identify whether I followed my process. This is where an approachable investing app can become more useful over time: not because it guarantees better outcomes, but because it lowers the effort needed to maintain a disciplined routine.
Where the simple approach reaches its limits
Plynk is not the right choice for every investor. Someone who needs advanced chart analysis, highly detailed order controls, extensive research tools, or a professional trading workflow may outgrow its approachable design. A traditional brokerage platform is usually better for users who already understand market mechanics and want more control over execution and analysis. In that situation, Plynk may feel intentionally limited rather than refreshingly simple.
It is also a poor fit for anyone looking for quick profits or constant trading stimulation. The educational focus may help slow down a beginner, but no app can prevent a user from making emotional decisions. If your main goal is to follow rapid price changes, compare sophisticated technical indicators, or manage a complex strategy, you should choose a platform built for that purpose instead of expecting this one to become something it was not designed to be.
There is a subtler limitation too: an intuitive presentation can make difficult decisions feel easier than they really are. When information is well organized, I may feel more confident before I have actually done enough research. I treat the app’s explanations as a starting point, not a complete investment thesis. For larger sums or complicated situations, I would look beyond the app and consider qualified financial guidance.
Users should also think about how much independence they want. Plynk is appealing when I want help understanding the basics, but investors who prefer to build their own detailed research system may find the guided style less satisfying. The trade-off is clear: less intimidation and less setup on one side, potentially less depth and customization on the other.
What the current app experience suggests
The current version is 4.4.2, and the overall product feels aimed at reducing the first barriers to investing. I would not judge it by the standards of a specialist trading terminal. Its success depends on whether it helps a person move from uncertainty to a sensible, informed routine without making the process feel inaccessible.
The developer, Digital Brokerage Services LLC, has positioned the product around intuitive tools and education, and that combination is visible in the way I would naturally use it. I would open it when I need a clearer explanation, a straightforward way to review my investing activity, or a calmer place to begin researching. I would not rely on it as my only source of financial knowledge, and I would not assume that a smooth experience means every available choice is suitable for me.
The free price makes experimentation easier, especially for someone comparing investing apps before choosing a regular home for their money. Still, “free” should not be interpreted as “without financial consequences.” The important costs are connected to the investments and decisions made through the app, so I would read all relevant terms and understand the transaction before proceeding. A free download is only the beginning of the evaluation.
The Everyone age rating also reflects how broadly approachable the app is, but younger or inexperienced users still need appropriate financial supervision and education. A friendly interface should encourage better questions, not remove the need for responsible decisions. I would be comfortable suggesting it as a learning-oriented starting place, while making clear that investing remains a serious activity.
Who should choose it, and who should look elsewhere
I would recommend Plynk to a beginner who wants investing explained in ordinary language, prefers a less intimidating interface, and is willing to develop a long-term habit rather than chase daily movements. It can also suit an existing investor who wants a simpler secondary app for learning or for introducing a family member to basic concepts, provided that person understands the limits of a beginner-focused platform.
I would steer away from it if you already depend on advanced analysis, need extensive customization, or make frequent, highly specific trades. In those cases, a full-service brokerage or specialist trading app will probably save time and provide the control you actually need. I would also skip it if you are unwilling to read, reflect, and accept risk; no amount of app simplicity can compensate for that missing foundation.
Before committing to regular use, I would spend one session exploring the educational material and another reviewing the account workflow. Ask yourself whether the explanations improve your understanding or merely make the buttons easier to press. That distinction is important. The app is at its best when it helps you think, not when it encourages you to act faster than your knowledge allows.
My verdict after building a repeatable routine
Plynk is strongest as a confidence-building investing companion, not as an advanced trading workstation. I appreciate the way it brings education closer to action, because many beginners stop before investing simply because the language feels too complicated. Used with a written plan, limited checking, and a pause before purchases, it can make the first steps feel manageable without pretending that investing is effortless.
Its limitations are part of the same design choice that makes it approachable. The user who wants depth, complex controls, or a highly technical research environment will likely prefer a conventional brokerage alternative. The user who wants a clear starting point and a repeatable weekly habit may find the trade-off worthwhile.
My final recommendation is to treat Plynk as a structured beginning. Use it to learn the vocabulary, review your choices, and create a process you can follow when markets are quiet as well as when they are noisy. If that is what you need, the free Finance app is an appealing place to start. If you are already an advanced investor, its clarity may be pleasant, but its simplicity may eventually become the reason you move on.
Frequently Asked Questions
What is Plynk: Grow as an Investor?
Plynk: Grow as an Investor is an investment app designed to make investing easier for beginners. It typically combines educational explanations with access to investment products, helping users understand concepts such as stocks, funds, risk, diversification, and long-term growth. Its simple presentation can be useful for first-time investors, although users should remember that investing involves risk and returns are never guaranteed.
Is Plynk suitable for beginner investors?
Plynk is primarily aimed at people who are new to investing and want a more approachable way to learn while managing investments. The app’s educational content and straightforward interface can make financial terminology less intimidating. However, beginners should still research each investment, understand fees and potential losses, and avoid investing money they may need for rent, bills, emergencies, or other essential expenses.
What can I invest in through Plynk?
The investments available through Plynk may depend on your country, account eligibility, and the services currently supported by the platform. Depending on the region, users may find access to products such as individual shares, exchange-traded funds, or other investment options. Before downloading, check the official listing and current terms to confirm which assets, markets, trading features, and account types are available to you.
Does Plynk charge fees for using the app?
Plynk may apply fees or other costs depending on the account, transaction, investment product, currency conversion, or service you use. Some features may appear free while costs are included elsewhere, so it is important to review the latest pricing information before depositing money. Pay attention to trading charges, subscription costs, withdrawal fees, foreign-exchange fees, and any fund or regulatory expenses.
Is my money safe when using Plynk?
Plynk should not be treated like a traditional savings account because investments can lose value. The protection available to users depends on the company’s regulatory status, the country where the account is held, and whether money is invested or kept as cash. Review the app’s security information, privacy policy, investor-protection arrangements, and withdrawal rules before committing funds, and use strong account-security practices.


